


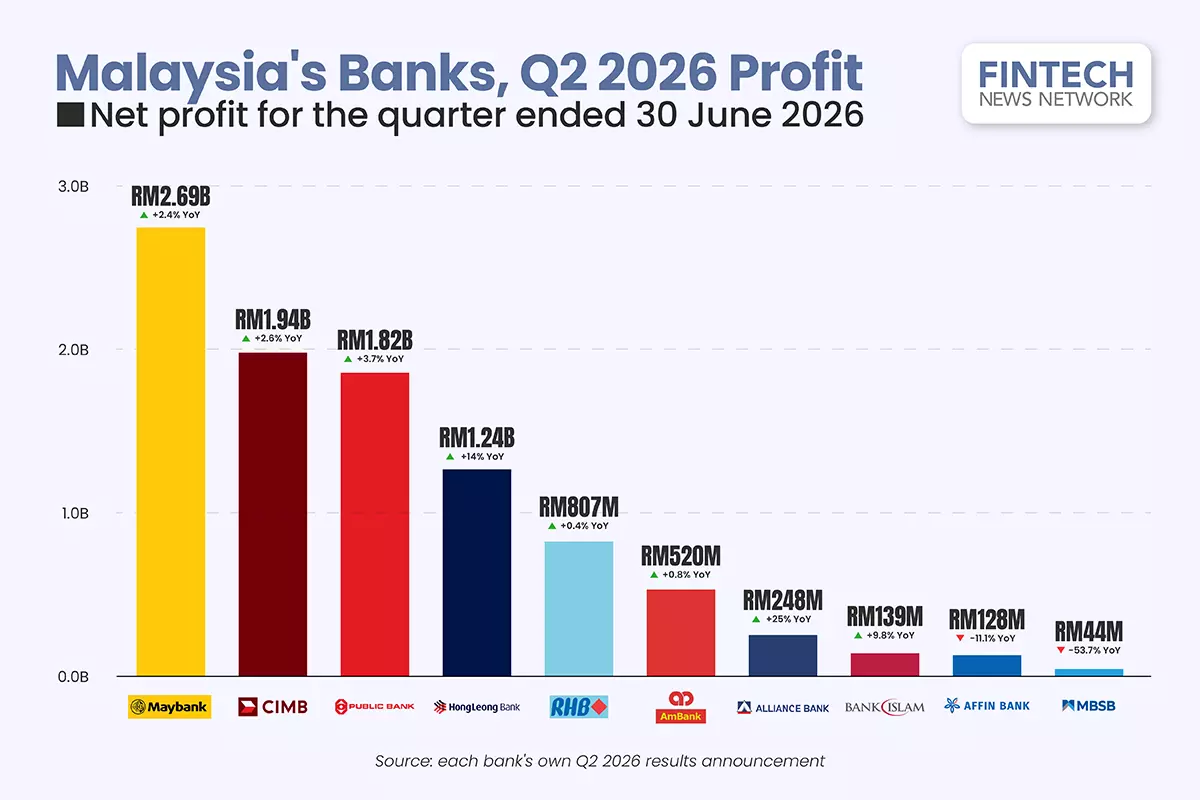
The 10 Bursa-listed Malaysian banking groups in this comparison collectively made about RM9.58 billion in net profit during the April-to-June quarter, roughly 3.6% more than the same group earned a year earlier.
Maybank alone contributed RM2.69 billion, or about 28% of the combined figure. CIMB and Public Bank followed with RM1.94 billion and RM1.82 billion respectively.
Together, the three accounted for roughly two-thirds of the profits in this comparison.

The growth ranking looks quite different. Alliance Bank’s profit jumped 25%, while Hong Leong Bank grew 14.2%. Affin Bank and MBSB were the only two to report lower earnings, with MBSB’s profit falling by more than half.
There is one wrinkle when comparing the results as Malaysian banks do not all follow the same financial year.
Maybank, Public Bank, CIMB, RHB, Bank Islam, Affin Bank and MBSB report April to June as their second quarter of FY2026.
Hong Leong Bank closes its books on 30 June, making the same period its 4QFY2026. AmBank and Alliance Bank use a March year-end, so they call it 1QFY2027.
Every figure below covers the three months ended 30 June 2026, regardless of the quarter label used by each bank.
How Malaysia’s Banks Ranked by Q2 2026 Net Profit
Maybank Still Makes the Most Money
Maybank was the biggest quarterly profit generator among the 10 groups reviewed, with RM2.69 billion in second-quarter net profit, up 2.4% from RM2.63 billion a year earlier.
Profit before tax rose 3.7% to RM3.64 billion, while return on equity improved to 12% from 11.6%.
The more interesting movement happened in costs and credit.
Net impairment provisions fell 51.4% to RM230 million, operating expenses declined 2.5%, and net interest margin improved by 10 basis points to 2.10%.
Wealth management fees rose 61.5% year on year, while investment banking-related fees increased 58.4%.
Maybank declared a first interim dividend of 31 sen per share, equivalent to a payout of about RM3.75 billion.
Profit growth of 2.4% is fairly modest, but the sheer size of Maybank’s earnings means it still generated more than a quarter of the combined profit in this comparison.

CIMB Takes Second Place
CIMB moved into second place with RM1.938 billion in net profit, up 2.6% from RM1.889 billion a year earlier.
Its quarterly revenue came in at RM5.56 billion, slightly below RM5.60 billion in the corresponding quarter.
Compared with the first quarter, total income rose 2.8%. Non-interest income increased 6% to RM1.83 billion, while net interest income grew 1.3% to RM3.73 billion.
Asset quality strengthened too. CIMB’s gross impaired loan ratio fell to 1.6%, which the group described as an all-time low.
The group declared a first interim dividend of 19.65 sen per share, translating to a payout of about RM2.1 billion.
Only around RM114 million separated CIMB and Public Bank in quarterly profit, making second place much closer than Maybank’s lead at the top.

Public Bank Keeps Profit Growth Steady
Public Bank recorded RM1.825 billion in net profit, up 3.7% from RM1.760 billion a year earlier.
Revenue increased to about RM7.61 billion, while non-interest income rose 21.3%. Higher unit trust sales and unit trust management fees were among the main contributors to the increase.
Its first-half numbers continued to show unusually low levels of impaired lending.
Public Bank reported a gross impaired loans ratio of 0.54%, against an industry average of 1.43%, while loan loss coverage stood at 138.9%. Total loans reached RM458.9 billion.
A first interim dividend of 10.5 sen per share was declared, representing a payout of about RM2.04 billion.
Public Bank did not produce the fastest profit growth, but its combination of RM1.82 billion in quarterly earnings and low impaired-loan levels keeps it firmly among the sector’s largest profit generators.

Hong Leong Posts the Strongest Growth Among the Top Four
Hong Leong Bank stood apart from the other billion-ringgit earners.
Net profit for the April-to-June period reached about RM1.24 billion, up 14.2% from roughly RM1.09 billion a year earlier.
The quarter closed Hong Leong Bank’s FY2026, with full-year profit after tax rising 6% to RM4.53 billion.
Gross loans and financing grew 7.7% year on year to RM226.3 billion, while the gross impaired loan ratio remained low at 0.57%.
A final dividend of 80 sen per share was declared.
Maybank, CIMB and Public Bank all grew quarterly profit by less than 4%. Hong Leong’s 14.2% increase puts some distance between it and the other banks at the top of the profit table.

RHB Bank Barely Moves in Q2
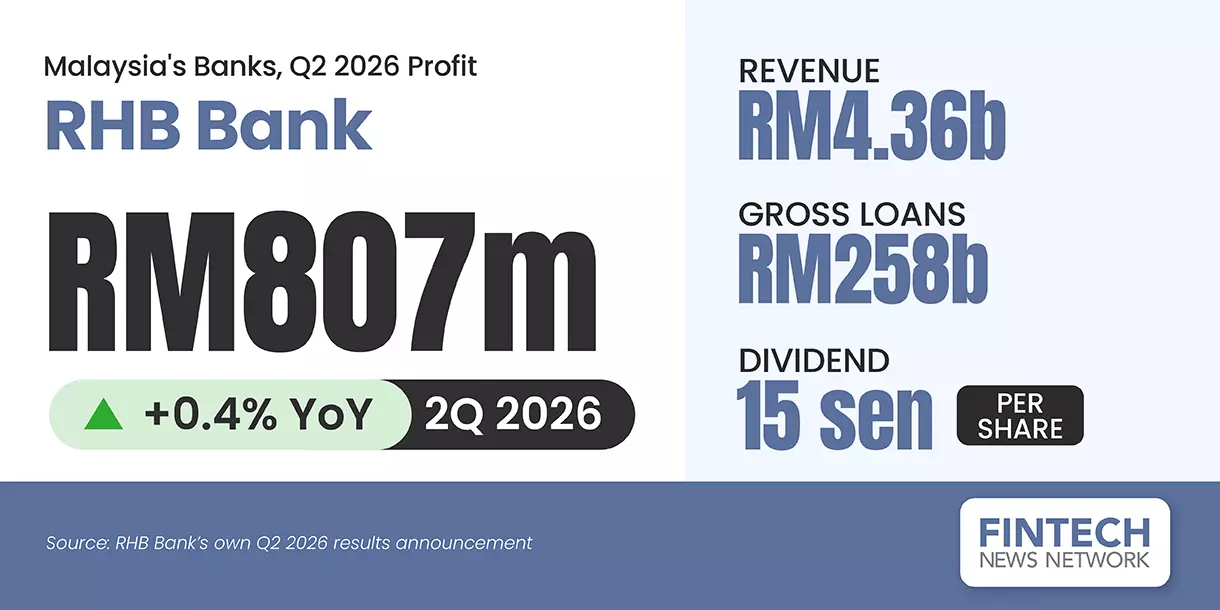
RHB Bank’s second-quarter net profit came in at RM807.15 million, compared with RM803.50 million a year earlier.
The increase works out to just 0.45%, making RHB one of the closest to flat earnings in the comparison. Revenue slipped to RM4.36 billion from RM4.50 billion.
The first-half numbers were considerably better. Net profit for the six months rose 7.1% to RM1.66 billion, while expected credit losses fell 12.7%. RHB declared an interim dividend of 15 sen per share.
The gap between its quarterly and first-half growth shows how much stronger RHB’s first quarter had been.
Its 1QFY2026 net profit rose 14.2% year on year, leaving the June quarter looking much quieter by comparison.
AmBank Posts a Quiet Quarter
AmBank’s PATMI edged up 0.8% to RM520.2 million, from RM516.2 million a year earlier.
Net income grew 2.8% to RM1.33 billion and net interest income increased 4.3% to RM964.7 million, supported by loan growth. Gross loans, advances and financing expanded 7% year on year to RM147.8 billion.
Margins moved the other way. Net interest margin narrowed to 1.93% from 2.01% as asset yields softened.
AmBank also booked an additional RM52.5 million overlay provision for exposures it considered potentially vulnerable to sustained geopolitical tensions.
Higher overlay reversals in retail banking helped offset that, leaving overall net impairment charges marginally below the corresponding quarter.
With profit growth of less than 1%, AmBank joined RHB among the banks whose bottom lines barely shifted from a year earlier.

Alliance Bank Records the Fastest Profit Growth
Alliance Bank may rank seventh by absolute profit, but no bank in the comparison grew earnings faster.
Net profit after tax jumped 25% to RM248.3 million, compared with about RM198.7 million a year earlier. Revenue rose by a much smaller 2.5% to RM630.9 million.
Lower credit costs explain much of that gap.
Alliance said earnings benefited from better credit performance and recoveries from its corporate portfolio, alongside loan growth and higher client-based fee income. Net credit cost improved to just 0.3 basis points.
Fee businesses contributed too.
Wealth management fees rose 46.6% and banking services fees increased 75.8%, while gross loans and unrated bonds expanded 9.5%.
A 2.5% rise in revenue turning into a 25% jump in profit makes Alliance’s result one of the more interesting of the quarter.
Less money was being absorbed by credit costs, allowing a relatively modest increase in income to produce a much larger increase at the bottom line.

Bank Islam Bounces Back in Q2
Bank Islam reported RM139.12 million in second-quarter net profit, up 9.8% from RM126.69 million a year earlier.
Revenue rose 6.3% to RM1.36 billion, while profit before tax increased to RM184.93 million from RM170.83 million.
Higher net fund-based income, fees and commission income contributed to the improvement, alongside gains on financial asset revaluations and foreign exchange.
The quarter also reversed some of the weakness seen at the start of the year. Bank Islam made RM115.03 million in 1QFY2026, down from RM126.27 million a year earlier.
After the Q2 recovery, first-half net profit reached RM254.15 million, only 0.5% higher than the same six months of 2025.
The 9.8% quarterly increase therefore looks stronger than Bank Islam’s first-half growth, which remained almost flat.

Affin Bank Grows Revenue but Profit Falls
Affin Bank was one of only two groups to report lower quarterly profit.
Net profit dropped 11.1% to RM127.52 million, from RM143.49 million a year earlier, even though revenue increased 5% to RM647.21 million.
Affin attributed the decline mainly to a RM38.1 million increase in impairment allowances and an RM18.4 million reduction in its share of associates’ results. Higher net income and lower operating expenses cushioned part of the impact.
The bank was still expanding its lending business with loans, advances and financing reached RM84.1 billion in the first half, up 13.6% year on year.

MBSB Posts the Steepest Decline
MBSB had the weakest year-on-year profit comparison of the 10 groups.
Net profit attributable to shareholders fell 53.7% to RM44.22 million, from RM95.56 million a year earlier.
Revenue declined 11.1% to RM829.94 million, while profit before tax dropped to RM61.42 million from RM133.81 million.
The first-half comparison was similarly weak. Attributable net profit fell to RM74.36 million from RM180.24 million in the first six months of 2025.
MBSB declared a dividend of 0.86 sen per share, compared with 2 sen for the corresponding quarter last year.
MBSB’s 53.7% decline was the steepest among the 10 groups, well beyond Affin Bank’s 11.1% drop.

Editor’s Note:
We reviewed 10 non-overlapping Bursa-listed Malaysian banking groups that are either licensed commercial or Islamic banks, or the listed holding companies of such banks. Each banking franchise is counted once.
Where the operating bank is separately listed, we use that bank rather than its listed parent. Hong Leong Financial Group is therefore excluded because Hong Leong Bank is already included.
CIMB Group Holdings, AMMB Holdings and MBSB Berhad are used because CIMB Bank, AmBank (M) and MBSB Bank are not separately listed.
Investment-bank-only listings such as Kenanga Investment Bank and Hong Leong Capital are outside the comparison, as are unlisted domestic banks, foreign-owned Malaysian bank subsidiaries and development financial institutions.
Net profit refers to profit attributable to ordinary equity holders for the three months ended 30 June 2026.
Featured image: Edited by Fintech News Malaysia based on an image by jamesteoh1976 via Magnific.
