Close Menu
    • Fintech Startups Malaysia – List of Fintech Startups and Fintech Companies in Malaysia
    • Fintech Jobs Malaysia
    • About Fintech News Network
    • Work With Us
    • Contact Us
    • Media Kit
    • Advertise With Us
    • Fintech Malaysia Newsletter
    • Submit Fintech Startup
    • Submit Press Release
    • Submit Interview Request
    • Submit Fintech Event
    • Webinar Inquiry APAC
    LinkedIn Facebook X (Twitter) YouTube RSS
    • About
      • About Fintech News Network
      • Work With Us
    • Contact Us
    • Media Kit
    • Advertise With Us
    • Fintech Malaysia Newsletter
    • Submit Press Release
    • Submit
      • Submit Press Release
      • Submit Fintech Startup
      • Submit Interview Request
      • Submit Fintech Event
      • Submit Your Vacancy
      • Webinar Inquiry APAC
    • Fintech Events in Malaysia
    • MY Fintech Startup Directory
    Fintech News Malaysia
    part of Fintech News Network

    Fintech News Network

    LinkedIn Facebook X (Twitter) Instagram YouTube TikTok RSS
    Free Newsletter
    • Blockchain
    • Digital Banking
    • Lending
    • Payments
    • Insurtech
    • Wealthtech
    • Regtech
    • Report
    • Startups
    • Events
    Fintech News Malaysia

    Fintech News Network

    Home»Digital Transformation»Digital Transformation: Ditching the “Build vs. Buy” Mentality for a Hybrid Approach
    Digital Transformation Sponsored

    Digital Transformation: Ditching the “Build vs. Buy” Mentality for a Hybrid Approach

    Fintech News MalaysiaFintech News MalaysiaJuly 22, 20224 Mins Read
    LinkedIn Facebook Twitter Copy Link Telegram Email
    Digital Transformation- Ditching the “Build vs. Buy” Mentality for an Hybrid Approach
    Share
    LinkedIn Facebook Twitter Telegram Copy Link Email
    Free Newsletter

    Get the hottest Fintech Malaysia News once a month in your Inbox

    Banks embarking on a digital transformation journey face the tough dilemma of having to choose between building platform components in-house or buying them.

    But instead of these two historically binary options, there is a third alternative that combines the best of both worlds: the accelerated build, a new paper by engagement banking platform provider Backbase, says.

    The whitepaper, titled Accelerated build: Bridging the build vs. buy gap, introduces the concept of accelerated build, an approach that provides banks with both a quick time-to-market and high degree of customisability.

    According to the paper, while building in-house gives financial institutions full control of the required capabilities and a high degree of customisation, allowing them to create innovative, custom-made solutions and potentially stand out from competitors, it is also very costly and time consuming.

    Backbase estimates that the total cost of ownership for a basic banking offering built in-house ranges between US$1.2 million to US$1.6 million annually.
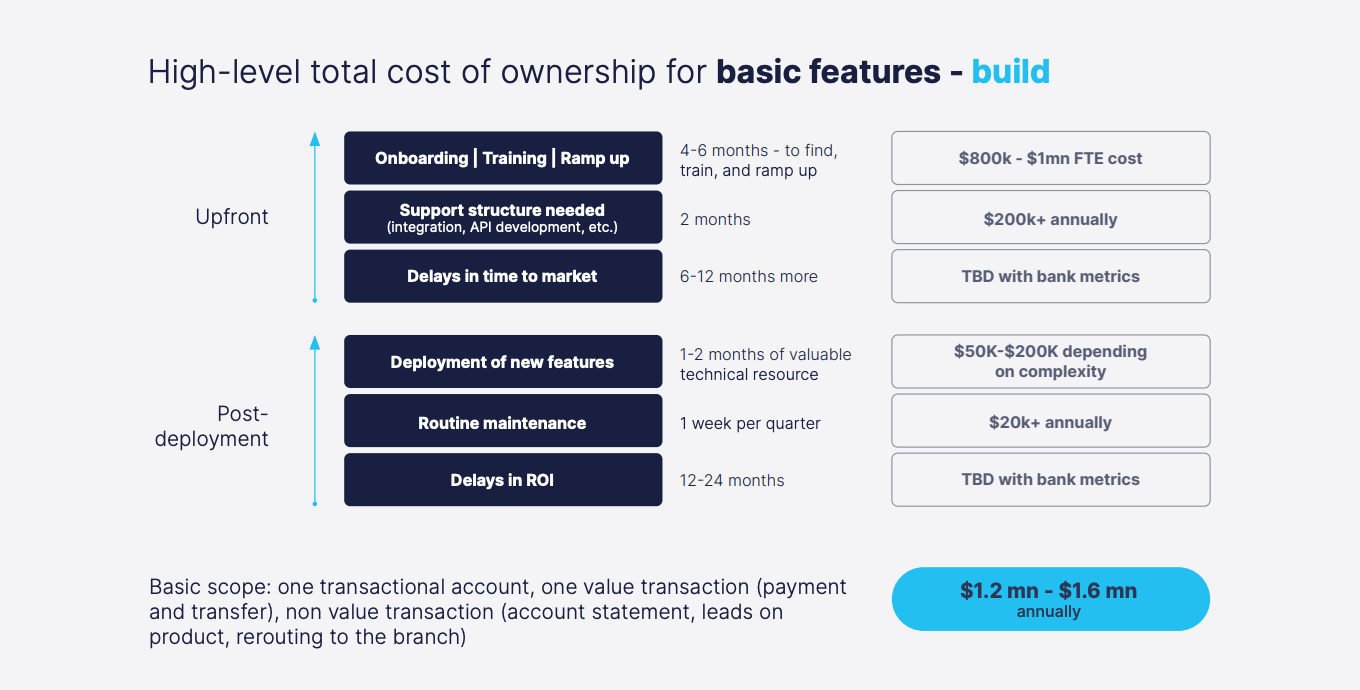
    Total cost of ownership for basic features - build, Source: Backbase
    Total cost of ownership for basic features – build, Source: Backbase

    The buy option, on the other hand, allows banks to leverage the resources of best-in-class partners and benefit from a faster time-to-market, as well as a more predictable budget.

    However, the approach also comes with a number of shortcomings, including the inability to create deeply customised customer experiences, origination/ distribution features, and business functions, such as sales and management.

    Critics often claim that bought solutions are cookie-cutter experiences that fail to provide clients with the differentiating elements that make banks stand out from the pack.

    The accelerated build approach

    Considering these two approaches’ advantages and weaknesses, Backbase argues that the best solution might be by embracing a hybrid strategy and adopting what it calls the accelerated build.

    Essentially, the accelerated build involves buying a vendor platform first and then customising it later.

    This approach offers the best results by taking the best parts of the build and buy options and creating a hybrid that gives banks speed, flexibility, and customisability, all while minimising risk and cost, it says.

    Buying an out-of-the-box offering first provides banks with a strong foundational backbone and accelerates the initial release.

    Banks aren’t tech providers and should consider buying some components of their stack off the shelf and outsourcing commodity capabilities to relevant providers that can do it better, Backbase says, focusing instead on value-added activities and products.

    When the delivery model grows and the bank has learnt more about its customers, the bank can then start tailoring these solutions to fit its specific needs and extend the options that are missing from the original provider’s solution.

    At the end of the whole process, the bank gets a platform with a fully realised, end-to-end value proposition, gained a faster time-to-market and lowered its costs.

    Backbase shares the following recommendation of which components it believes banks should buy and build:

    What should banks build and buy, Source: Backbase
    What should banks build and buy, Source: Backbase

    A six-dimensional framework approach

    To help banks figure out which approach is best for them, Backbase proposes a six-dimensional framework to thoroughly assess an organisation’s objectives and capabilities to determine the most appropriate implementation option:

    • The first dimension, Strategic Advantage, covers the bank’s reasoning behind creating a new engagement platform, as well as its digital vision and articulation with its maturity;
    • The Criticality to Business dimension focuses on assessing the engagement banking platform’s creation as a business imperative while identifying critical processes and risks associated with implementation;
    • The third dimension, Partnership Capacity, aims to understand the bank’s ecosystem, ability to manage partnerships and the marketplace, and aptitude to foster innovation;
    • The Delivery Model and Capabilities dimension looks at the bank’s internal capabilities to understand the organisation, the skill depth, and the learning curve;
    • Technology Complexity involves considerations of the backbone of the engagement banking vision across all viewpoints, including requirements, technologies, architecture, tooling, integration, and the implementation ecosystem;
    • Finally, Cost Advantage involves assessing the total cost of the effort, encompassing the ecosystem setup, as well as the implementation and outgoing costs of creating the engagement banking platform.


    downlaod the whitepaper


    Featured image credit: Edited from Freepik

    accelerated build Backbase
    Share. LinkedIn Facebook Twitter Telegram Copy Link Email

    Author

    Avatar photo
    Fintech News Malaysia
    • Facebook
    • X (Twitter)

    Related Posts

    28% of APAC Bank Customers Aren’t Satisfied. How Do You Keep Them?

    November 19, 2026

    What Would It Take for Banks to Recover Their AI Agents?

    November 12, 2026

    Malaysia & 3 Other Asian Countries Get Their Own TikTok Shop App

    November 6, 2026

    AWS Plans AI Rollout for Up to 445,000 Malaysian Civil Servants

    November 4, 2026

    M+Global Launches Headstart Campaign with Cash and Share Rewards

    November 2, 2026

    Tauke Tabung or Hutang Slayer? Discover Your Financial Purr-sona With AEON Bank’s Neko Sensei

    October 30, 2026

    What Happens to Your Crypto If a Digital Asset Custodian Fails?

    October 27, 2026

    You Can’t Just Apply for HLB’s New Opus Card—‘The Card Will Choose You’

    October 26, 2026
    AI Security Sponsored

    What Would It Take for Banks to Recover Their AI Agents?

    November 12, 2026
    Fintech Malaysia Newsletter
    Subscribe to the most important Fintech Malaysia News
    Follow Us
    • LinkedIn
    • Facebook
    • X / Twitter
    • Instagram
    • YouTube
    • TikTok
    Featured Fintech Webinar

    Who Is Responsible When AI Agent Makes A Payment

    MY Fintech Startup Directory

    Malaysia Fintech Startup Directory

    Featured Fintech Whitepaper

    Navigating today's era of AI and agentic banking

    Featured Fintech Reports

    Malaysia faces its biggest fintech test yet. Download Malaysia Fintech Report 2026

    59% open to AI agents. New MAS AI guidelines. Singapore Fintech Report 2026

    The AI Resilience Blueprint: Governing and Recovering Agentic Financial Systems

    LexisNexis Solutions

    AI Sponsored

    Who Really Controls a Bank’s AI? Huawei Pitches an Answer

    Fintech News Indonesia 21 October 2026
    Featured Webinar Replay

    How Fintechs Can Thrive in the Age of AI

    Who Wins the Next Era of Embedded Finance?

    Featured Fintech Videos

    How Do Institutions Keep Their Crypto Safe

    Is BNPL The Greatest Evil?

    Hong Leong's New Card Is Forged in Fire And You Can't Apply for It

    Whitepapers & E-Books
    State of Digital Trust: AI Governance Benchmark
    State of Digital Trust: AI Governance Benchmark
    Sumsub
    Upcoming Fintech Events
    Country
    Who Is Responsible When an AI Agent Makes a Payment?
    December 2, 2026
    Featured Online
    InsureTek 2027 - Malaysia
    April 7, 2027
    Malaysia
    -
    Kuala Lumpur
    Cyber Revolution Summit (CRS 2027) Malaysia
    April 8, 2027
    Malaysia
    -
    Kuala Lumpur
    Digital Transformation Summit 2027
    April 14, 2027
    Malaysia
    -
    Kuala Lumpur
    BFSI IT Summit 2027
    April 15, 2027
    Malaysia
    -
    Kuala Lumpur
    Promote Event View More
    Fintech Jobs
    Rating
    TNGD Remittance - Head of Compliance (With Money Services Business Background)
    Kuala Lumpur
    TNG Digital
    Global Partnerships Manager (BD)
    Kuala Lumpur
    Tranglo
    Head, Market & Liquidity Risk
    Petaling Jaya
    GXBank
    Head, Consumer Deposits & Payment
    Kuala Lumpur
    AEON Bank
    Sr. Distribution Partner Development Manager
    Kuala Lumpur, Full-time
    Amazon Web Services Malaysia
    View More
    Navigation
    • About Fintech News Network
    • Advertise With Us
    • Media Kit
    • Work With Us
    • Contact Us
    • Fintech Malaysia Newsletter
    • Submit Press Release
    • Submit Fintech Startup
    • Submit Fintech Event
    • Submit Your Vacancy
    • Submit Interview Request
    • Fintech Events in Malaysia
    • Malaysia Fintech Startup Directory – List of Fintech Startups and Fintech Companies in Malaysia
    • Privacy Policy / Disclaimer
    Other Fintech News Network Publications
    Fintech News Malaysia
    Fintech News Singapore
    Fintech News Hong Kong
    Fintech News Philippines
    Fintech News Network Indonesia
    Fintech News Network Australia
    Fintech News Switzerland
    Fintech News Baltic
    Fintech News Nordics
    Fintech News America
    Fintech News Network UAE
    Fintech News Africa
    Get Informed

    Subscribe to Updates

    Subscribe to the most important Fintech Malaysia News

    LinkedIn Facebook X (Twitter) YouTube RSS
    • About Fintech News Network
    • Advertise With Us
    • Media Kit
    • Work With Us
    • Contact Us
    • Fintech Malaysia Newsletter
    • Submit Press Release
    • Submit Fintech Startup
    • Submit Fintech Event
    • Submit Your Vacancy
    • Submit Interview Request
    • Fintech Events in Malaysia
    • Malaysia Fintech Startup Directory – List of Fintech Startups and Fintech Companies in Malaysia
    • Privacy Policy / Disclaimer
    © 2015 - 2026 Copyright CK Finanzpro GmbH. All Rights reserved.

    Type above and press Enter to search. Press Esc to cancel.